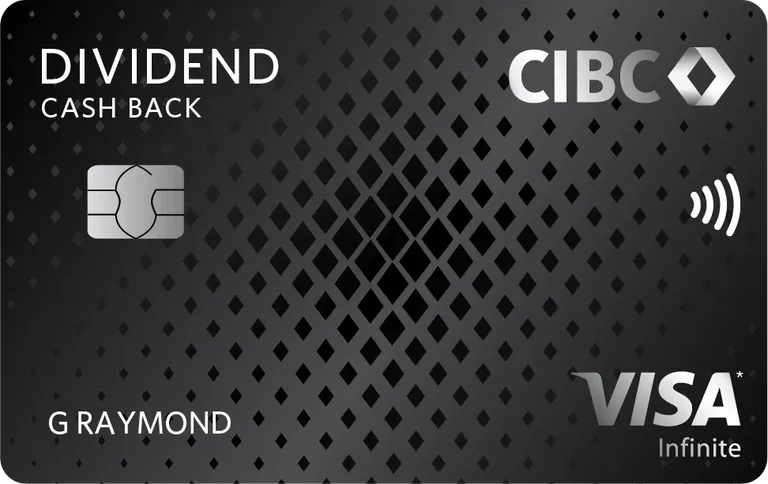
The Dividend Visa Infinite is the card I'd point a household to when the two biggest line items on the statement are groceries and gas. At 4% on both, plus EV charging, from what I can tell it sits near the top of the big-bank cash back cards for those two categories, and the first year costs nothing.
The part I'd want every applicant to read is the ceiling. The 4% and 2% rates stop once you hit $20,000 a year in those categories (or $50,000 in total card spending), and everything after that earns 1%. For a typical family that limit is comfortable; for a big spender it means this card tops out quickly.
Welcome offer
CIBC is advertising up to $350 in value for new cardholders, made of three parts. The main one is 10% cash back on net purchases in your first 4 monthly statements, up to $2,000 in purchases, which works out to $200. Regular earn rates don't stack on top, so those first $2,000 earn 10% flat whatever the category.
The second part is a $50 bonus for setting up one recurring bill payment (a phone, internet or streaming bill) that posts within the first 4 statements. The third is a first-year annual fee rebate worth $120, which also covers up to 3 authorized users added when you apply. The offer applies to cards approved from July 16, 2026, shows no end date, and is off the table if you opened, transferred or cancelled another CIBC Dividend card in the last 12 months.
The $2,000 cap is low enough that ordinary spending clears it in a month or two, so there is nothing to sprint for. Move a phone or streaming bill onto the card in the first statement to lock in the $50, and keep it there afterwards, since recurring payments earn 2%.
Fees & eligibility
The card runs $120 a year, rebated in the first year as part of the welcome offer. Authorized users cost $50 each, up to 3, and their first-year fees are rebated too if you add them on the application. If you bank with CIBC, a CIBC Smart Account at Tier 2 or Tier 3 can rebate the fee every year (up to $50 at Tier 2, up to $139 at Tier 3 for the primary cardholder).
Approval needs a personal income of $60,000 or household income of $100,000, and the card comes with a minimum credit limit. Interest is 21.99% on purchases and 22.99% on cash advances and balance transfers (21.99% for Quebec residents). Purchases made in a foreign currency carry a 2.5% conversion fee, and the cash back only comes out ahead if you pay the balance in full each month.
Earning rewards
The top tier is 4% cash back at grocery stores and supermarkets, at gas stations, and on EV charging. The middle tier is 2% on local transit and ride sharing, restaurants and bars, recurring bill payments, and travel booked through CIBC by Expedia. Everything else earns 1%, with no limit on total cash back.
Categories follow how the merchant is coded by Visa, so a store classed as a supermarket earns 4% while a big-box retailer that also sells food may not. The 2% transit rate covers subways, streetcars, taxis, limousines and ride sharing in Canada, but not airlines, car rentals or cruises.
The weakness is the 1% base. Anything outside the categories earns half of what the Amex SimplyCash Preferred pays on everyday spending (2%), so this card works best as the grocery, gas and bills card rather than the only card in the wallet.
Redeeming rewards
Redemption is a statement credit on demand. Once your balance reaches $10, the primary cardholder can redeem any amount through CIBC Online Banking, the mobile app or by phone, and the credit lands within 5 days.
Cash back does not expire while the account is open and in good standing, and there is no limit on how much you can earn. Smaller balances under $10 can be redeemed by phone between December 1 and March 31. Authorized users earn for the account but cannot redeem.
Perks & benefits
Perks are everyday rather than travel. The most useful is Journie Rewards: link the card and save up to 10 cents per litre at participating Chevron, Ultramar, Pioneer and Fas Gas stations, on top of the 4% the card already pays on gas. The Benefits Guide breaks that down as 3 cents off at the pump plus 7 cents off a later fill-up once you collect 300 Journie points.
The card also carries the Visa Infinite package (24-hour concierge, the Dining Series and the Luxury Hotel Collection), a free Skip+ membership when linked, and discounts of up to 30% at Avis and 35% at Budget on Pay Now base rates. There is no lounge access, no travel credit and no foreign transaction fee waiver.
Insurance
The insurance package leans toward everyday purchases. Mobile Device Insurance covers a phone or tablet bought on the card for up to $1,000 per claim for 2 years, after depreciation and a 10% deductible. Purchase Security covers new items for 90 days, and Extended Protection doubles the manufacturer's warranty by up to one extra year.
For travel, it is thin. Out-of-province emergency medical pays up to $5,000,000, but only for the first 10 days of a trip and only if you are 64 or under; there is no medical coverage at all from age 65. There is no trip cancellation, trip interruption, flight delay or baggage coverage. Car rental collision and loss damage (MSRP up to $85,000, 48 days) and $500,000 common carrier accident insurance round it out.
My take
I'd get this card if groceries, gas and household bills are where most of your money goes; I'd skip it if you spend well past $20,000 a year in those categories or want travel insurance that does real work.
What I like is how directly it pays for a normal family budget. A household putting a few hundred dollars a month on groceries and a tank or two of gas earns 4% on exactly that, the first year is free, and the cash back can be pulled out any time from $10. Add Journie at the pump and the gas savings stack nicely.
What I'd keep in mind is the shape of the limits. Once you pass $20,000 a year in the bonus categories, the card becomes a 1% card for the rest of the year, and the 1% base is weak for everything else. I'd pair it with a no-FX card for trips abroad and with separate travel medical insurance for anything longer than 10 days.
The good
- 4% on groceries, gas and EV charging, plus 2% on dining, transit and bills
- First-year fee rebated, plus 10% back on your first $2,000
- Redeem any time from $10, and cash back never expires
The catch
- Bonus rates stop after $20,000 a year in categories or $50,000 in total spend
- Only 1% on everything outside the categories
- Travel medical is 10 days, under 65 only; 2.5% FX fee