- Wealthsimple's prepaid card is now a Visa and its 1% cash back ended October 1, 2025, but it still has no FX fee and refunds ATM fees worldwide with no limit (great for Thailand and Mexico).
- The EQ Bank Card is the only one here with cash back on everything (0.5%), but it doesn't refund ATM fees outside Canada.
- Wise is the tool for holding foreign currencies; free ATM withdrawals stop at 100 CAD a month.
- KOHO's free plan (1.5% FX fee) and the Neo Money card (3% FX fee) don't make sense for spending abroad.
I first wrote this post in January 2025, and a lot has changed since then. Wealthsimple renamed its card, moved it to Visa and ended the 1% cash back I loved so much 🥲
So I went back through every card's own pages to see whether my ranking still holds. Spoiler: it mostly does, just for different reasons.
Picking a travel prepaid card still comes down to two things: exchange rates and cash withdrawal fees. Here is how my three picks (and two cards that didn't make it) compare in October 2026.
| Card | Monthly fee | FX fee | ATM fees | Interest on balance | Cash back |
|---|---|---|---|---|---|
| Wealthsimple Visa Platinum Prepaid | $0 | 0% | Operator fees refunded worldwide, no limit | 1.25% to 2.25% | None |
| EQ Bank Card | $0 | 0% | Canadian operator fees refunded (5 a month, up to $5 each) | 1.50% (2.75% with pay deposit) | 0.5% on everything |
| Wise Multi-Currency Card | $0 | Conversion fee from 0.19% | Free up to 100 CAD a month, then 2.69 CAD + 2.69% | 2.22% on CAD (opt-in) | None |
| KOHO (free Core plan) | $0 | 1.5% | $2 to $3 out-of-network fee | 2% (opt-in) | 1% in three categories |
| Neo Money™ Card | $0 | 3% | Free today, $1.50 from January 1, 2027 | 0.1% | 1% on gas and groceries (capped) |
Let's dive right in.
1. Wealthsimple Visa Platinum Prepaid Card
The Wealthsimple Visa Platinum* Prepaid Card is still my top pick for travel, even without the cash back. If you knew it as the Wealthsimple Cash Mastercard, it's the same idea: the card spends from your Wealthsimple Chequing balance, and Wealthsimple is moving everyone from Mastercard to Visa in phases.
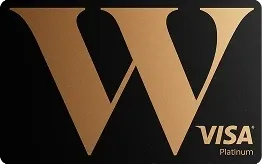
The 1% cash back ended on October 1, 2025. That one hurt, because it was the main reason I called this card a no-brainer.
What's left is still very good. There's no foreign transaction fee, so foreign purchases are charged at the network's exchange rate. Wealthsimple also now refunds ATM operator fees worldwide, with no limit on the number or the amount.
Here's an example from when it was still a Mastercard: a $100 USD purchase at Target.

I was charged 1 USD = 1.3614 CAD, while Google's spot rate at the time was 1 USD = 1.358 CAD. That's roughly 0.25% extra, far below the 2.5% FX fee most Canadian credit cards charge (it still surprises me how many Canadians don't know they pay it).
With the old 1% cash back, that purchase actually came out slightly ahead. Those days are gone, but paying close to the spot rate is still the whole point of a travel card.
Cash is where this card shines now. Here's me withdrawing 2,000 New Taiwan Dollars from an ATM in Taiwan.

The rate was a little worse than on a purchase, which is normal for a withdrawal. But what are the odds of finding a better rate at a currency exchange kiosk, especially past midnight?
(Why did I need cash at midnight? Let's not ask.)
Back then you could still get hit with a $2 to $3 fee from the ATM itself, which is why I wrote my free ATMs around the world post. Today Wealthsimple refunds those operator fees too, usually within 3 to 4 business days.
Your balance also earns interest: 1.25% on the basic tier, up to 2.25% for clients with $500,000 or more at Wealthsimple, plus 0.5% on the lower tiers when you direct deposit $2,000 in 30 days. The money is held in trust with CDIC member institutions, covered up to $1 million combined in Wealthsimple's words.
Two small catches. It's a Visa now, so it won't work in-warehouse at Costco, and the app still isn't really my cup of tea (simple and fast, though).
More details are on its card page.
Funding methods
- Direct deposit
- Interac e-Transfer
- Wire transfer
- Mobile cheque deposit
- Cash at Canada Post (5,300+ locations)
Pros
- No foreign transaction fee
- ATM operator fees refunded worldwide, no limit
- 1.25% to 2.25% interest on the balance
- CDIC coverage up to $1 million combined
- Virtual card available
- Apple Pay
Cons
- No more cash back (ended October 1, 2025)
- Visa, so no Costco in-warehouse
- The app's UI still isn't my favourite
2. EQ Bank Card
The EQ Bank Card is still my second pick, and it's now the only card on this list that pays cash back on everything: 0.5%. There's no foreign transaction fee either, since purchases are converted at Mastercard's rate.
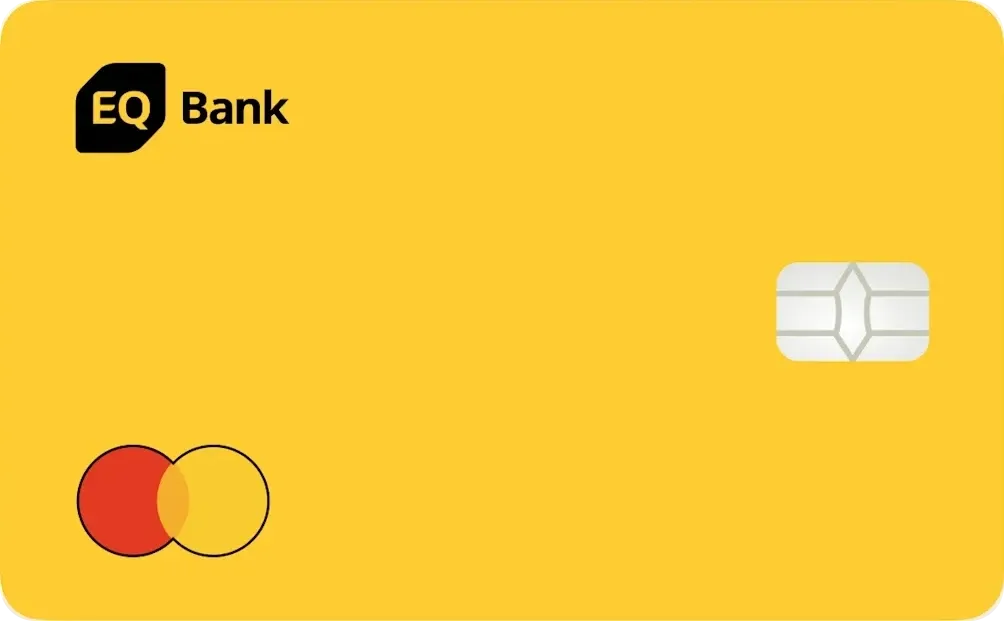
The big difference from Wealthsimple is cash. EQ Bank charges no ATM fee of its own and refunds what Canadian ATM operators charge (5 withdrawals a month, up to $5 each), but fees from ATMs outside Canada are not refunded.
Being part of a full banking app, EQ also gives you bill payments and cheque deposits. Since we're focusing on travel, that matters less here.
One thing I like about the EQ Bank Card is that it has its own balance, separate from your savings. You keep your main balance in the account and move only what you need onto the card.


This works as a safety measure if the card is ever lost or compromised. You can move the money back to savings right away, then call customer service to lock the card.
The card balance also earns the same interest as the Personal Account: 1.50%, or 2.75% when your pay is direct deposited. The card holds up to $10,000, ATM withdrawals are capped at $500 a day, and your money sits with Equitable Bank (EQ Bank's legal name), a CDIC member.
There is some room for improvement, though:
- The app is often sluggish. From signing in to everyday tasks, I find it slow.
- The app and website show transactions only in CAD. Unless you keep the receipt, you can't tell whether you got a good exchange rate.
More details are on its card page.
Funding methods
- e-Transfer
- Electronic funds transfer
- Cheque deposit
- Then a free, instant transfer from your EQ account to the card
Pros
- No foreign transaction fee
- 0.5% cash back on everything
- Canadian ATM fees refunded (5 a month)
- Interest on the card balance
- CDIC protection up to $100,000
- Apple Pay
Cons
- No refund of ATM fees outside Canada
- App is often slow
- Doesn't show the amount in the foreign currency
- No virtual card (physical card and Apple Pay only)
- $10,000 maximum card balance
3. Wise Multi-Currency Card
Lastly, the Wise card, which in Canada is a prepaid Visa. In 2025 I called it a great backup for merchants and ATMs that only take Visa. Now that Wealthsimple is on Visa too, Wise's real strength is something else: foreign currencies.

It uses the mid-market rate with a conversion fee from 0.19%, depending on the currency. On October 15, 2026, Wise's calculator showed 4.58 CAD in fees on 1,000 CAD spent in U.S. dollars, and spending a currency you already hold costs nothing.
Wise also shows its fees transparently and compares them with other providers. I truly appreciate this approach and wish more financial institutions did the same.

Before the card existed, Wise's whole focus was helping people exchange money at better rates than the big banks. That's why it can do what the other cards can't: hold, spend and send foreign currencies directly.
This means you can convert your money in advance. If you're planning a trip to Turkey and the lira looks cheap against the Canadian dollar, you can convert to TRY now and keep it until you travel.

Wise also pays interest now if you opt in: 2.22% on CAD and 3.4% on USD, as of Wise's February 25, 2026 rates.
Moving onto the negatives… the free ATM allowance got even smaller. You can withdraw up to 100 CAD a month for free (it was $350 when I first wrote this), and after that it's 2.69 CAD + 2.69% of the amount over 100 CAD. Still bizarre to me.
One thing I used to dislike: when you tried to add money, the app showed no free option at all. The trick was to set up Interac e-Transfer Autodeposit with your Wise login email and send yourself an e-Transfer.
Wise's pricing page now lists Autodeposit as free, so it's less of a secret. Here's the setup:


After this setup, you simply send an e-Transfer to your Wise email, and the money lands in your Wise account without any fees.
Overall, Wise does a lot, and that's a double-edged sword: the app has a steeper learning curve than the other two. Your money is held by Wise Payments Canada in a segregated account, and Wise itself says this safeguarding is not the same as deposit insurance.
More details are on its card page.
Funding methods
- Interac e-Transfer (Autodeposit is free)
- Domestic CAD payments
- Payments in other currencies to your Wise account details
- Wire / Swift (fees apply)
Pros
- Hold, convert and spend many currencies
- International money transfers
- Opt-in interest on balances
- Disposable virtual card
- Apple Pay
Cons
- No spending rewards
- Free ATM withdrawals only up to 100 CAD a month
- The app is complex
- Safeguarded funds, not deposit insurance
What about KOHO and Neo?
I checked two other popular prepaid cards for this update, and neither made the list for travel.
KOHO charges a 1.5% FX fee on its free Core plan. The paid plans (Extra at $12 a month and Everything at $14.75 a month, billed yearly) drop it to 0% and add one free ATM withdrawal outside Canada each month, but that's $144 or more a year for what the three cards above give you for free.
The Neo Money™ Card is worse for travel. Neo's fee schedule lists a 3% FX fee, and from January 1, 2027, each ATM withdrawal costs $1.50 unless you pay for a membership.
Both are fine for everyday budgeting, just not for spending abroad.
Final Thoughts
Prepaid cards and fintech have grown fast, mostly by offering what traditional banks don't. I personally find them very useful during my travels.

Even without the cash back, the Wealthsimple card is the one I'd take abroad: no FX fee, and every ATM fee refunded, which pays off fast in countries like Thailand and Mexico. EQ Bank is a close second if you want a little cash back and won't need much cash abroad, and Wise is the tool for holding foreign currency before a trip.
Which prepaid card do you travel with? Let me know in the comments below 🙂
* Trademark of Visa International Service Association, used under licence.
Written by
Jason
Jason is a Toronto-based points-and-miles writer who sleeps in hostels and redeems for suites: honest, frugal, lightly funny.