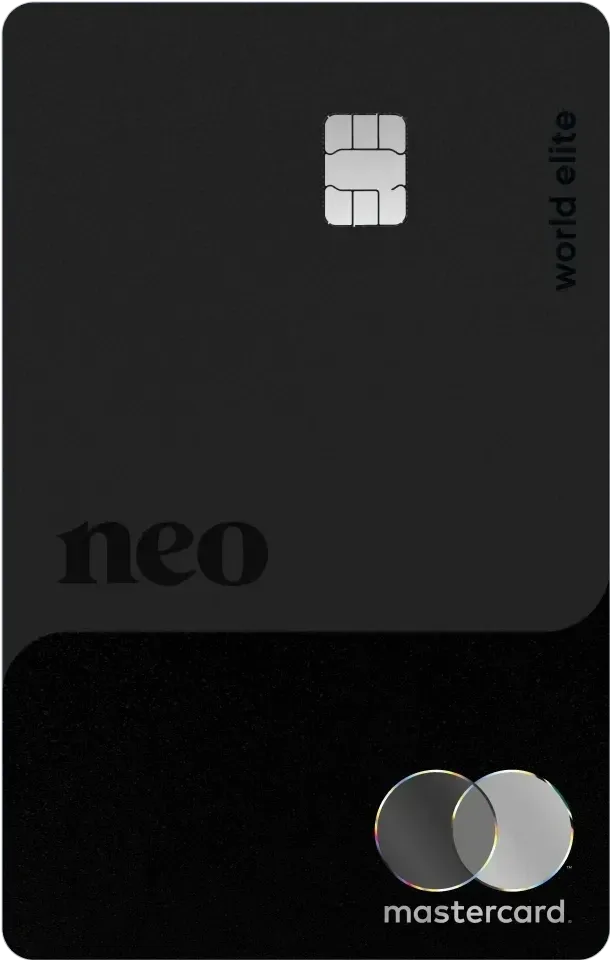
The Neo World Elite is one of the few cash back cards I'd look at for its rates alone: 5% on groceries, 4% on recurring payments and 3% on gas, with cash back you can spend the moment it lands. For a household that runs most of its budget through those three categories, that is a high return.
What gives me pause is what Neo leaves off the product page. Every bonus rate stops at a monthly spend limit, and the limit itself is only shown in the Neo app, so you can't judge the real ceiling before you apply. The $149 fee and a 3% foreign transaction fee also count against it.
Welcome offer
There is no welcome bonus on the Neo World Elite Mastercard right now. The product page leads with pre-approval and the earn rates rather than a sign-up offer, as of October 13, 2026.
Neo does run partner cashback offers inside its app, but those are ongoing merchant deals rather than a bonus for opening the card. Check the product page before applying in case a limited-time offer appears.
With no bonus to chase, the first thing to check after approval is the monthly spend limit on each bonus category in the Neo app. Those limits decide how much of your grocery, bill and gas spending actually earns 5%, 4% and 3%.
Fees & eligibility
The card runs $149 a year, and each additional cardholder costs $49 a year. The annual fee is charged on your first statement. Purchases carry an interest rate of 19.99% to 29.99% (19.99% to 25.24% in Quebec), set by Neo's assessment of your credit and province, and cash advances and balance transfers run 22.99% to 31.99%, with a 21-day grace period on purchases paid in full.
Eligibility is a personal income of $80,000 or a household income of $150,000, with a credit limit of up to $30,000 on approval. A secured version is available with at least $200 in security funds. Purchases in a foreign currency carry a 3% conversion fee, higher than the 2.5% most Canadian cards charge.
Earning rewards
Earning is built around three everyday categories: 5% cash back on groceries, 4% on recurring payments and 3% on gas. Everything else earns 1%, and cash back lands in your rewards balance as soon as a purchase posts.
Each bonus category has a monthly spend limit. Once you reach it, further spending in that category earns 1% until the limit resets the next month. Neo does not print the limits on its product page; they are shown in the Neo app.
Redeeming rewards
Cash back is available instantly in a separate Neo Rewards balance, with no points to convert and no minimum. You can move it to a Neo account, apply it as a statement credit, or spend it in the Neo Store.
A statement credit does not count as a payment, so the minimum payment is still due in a month you redeem. The rewards balance is lost if you cancel the card, so use it before closing the account.
Perks & benefits
The perks are thin for a $149 card. Mastercard Travel Pass gives a membership for airport lounge access, but every visit is paid, so it is a discount program rather than free lounge entry. There is no travel credit, no status and no foreign transaction fee waiver.
The day-to-day extras are app features: partner cashback offers at thousands of Neo merchants, an instant virtual card so you can spend before the physical card arrives, card controls, and a free Neo membership that unlocks premium features and higher savings interest rates on other Neo products.
Insurance
The insurance is the strongest part of the package, underwritten by Chubb. It includes emergency medical up to $1,000,000 for the first 14 days of a trip, trip cancellation and interruption up to $1,000 per person ($5,000 per trip), flight delay, delayed and lost baggage, and hotel burglary. Trips paid with the card or with points from the card's rewards program qualify.
Two limits matter. Medical coverage applies only if you, your spouse and children are under age 60, and none of the travel coverages is available to Quebec residents. Rental cars get primary collision and loss damage cover for up to 48 days on vehicles up to $65,000 MSRP, while purchase protection pays at most $1,000 per claim and $10,000 per account.
My take
I'd get this card if groceries and recurring bills are your biggest costs and you'll check the monthly limits in the app first; I'd skip it if you travel abroad often or want to know your earning ceiling before you apply.
On paper the rates beat most cash back cards in Canada, and instant cash back with no redemption hoops is a real convenience. The insurance is also broader than usual for a cash back card, with trip cancellation, flight delay and baggage cover alongside medical.
My hesitation is the hidden ceiling. Without the monthly limits on the product page, I can't tell you how much of a typical grocery bill earns 5%, and that number decides whether the $149 fee pays off. I'd also keep another card for travel: 3% on foreign purchases is steep, and the medical coverage ends at 14 days and stops applying at age 60.
The good
- 5% groceries, 4% recurring payments and 3% gas
- Cash back usable instantly, no minimum
- Trip cancellation, flight delay, baggage and primary rental cover
The catch
- Monthly limits on bonus rates are not published on the product page
- 3% foreign transaction fee
- Medical cover only for travellers under 60, 14 days