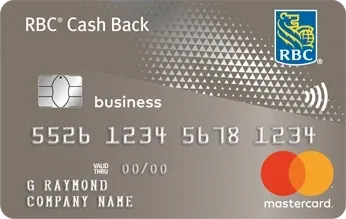
This is RBC's plain business cash back card: no annual fee, 1% back on every purchase, and the cash credited to the account each January without you asking. I'd point it at a sole proprietor or small business that banks with RBC, wants to separate business spending and build credit in the business's name, and would rather have cash than points.
What I'd flag is the ceiling. Cash back stops at $650 a year, which is $65,000 in spending at 1%, and you get only one additional card. Past that, or with a team that needs cards, it stops being the right tool.
Welcome offer
New accounts earn 2% cash back on purchases, including pre-authorized bill payments, for the first three months, verified on the RBC page on October 13, 2026. That is the standard 1% plus an extra 1%, with no minimum spend and no separate cap, and RBC prints no end date for the offer.
Two details from the fine print matter. The extra 1% applies to the first 3 full monthly statement periods in your first Annual Period, which RBC's program terms define as running from account opening to December 31, so an account opened late in the year may not get all three. The bonus also counts toward the card's $650 yearly cash back cap.
There is no spend target to chase, so simply move your regular business spending onto the card in the first three months. If you have a choice of timing, opening early in the calendar year gives the extra 1% the full three statement periods.
Fees & eligibility
The card has a $0 annual fee, and the one additional card it allows is also $0. RBC's business page prints no income or revenue minimum. Purchases carry a 19.99% interest rate and cash advances 22.99%, and RBC's cash back terms treat balance transfers as cash advances.
The product page links RBC's Business Credit Card Agreement for joint and several liability, so both the business and you as owner are responsible for the balance. A foreign transaction fee is not stated on the page, and at 19.99% interest a carried balance costs far more than 1% returns.
Earning rewards
The card earns a flat 1% cash back on all net purchases, including pre-authorized bill payments, with no categories to track. In the first three months the rate is 2%.
The catch is a combined cap of $650 in cash back per Annual Period (the calendar year), which RBC's terms tie to $65,000 in purchases at 1%. Spending beyond that earns nothing until the next January, and in your first year the cap applies to the part of the year after you open the account.
Redeeming rewards
Cash back is credited to the card account automatically every January as long as the balance is at least $25 and the account is in good standing; a smaller balance carries over to the next year. You can also call RBC to have the full balance credited at any time once it reaches $25.
The credit reduces the balance but does not count toward your minimum payment for that statement.
Perks & benefits
The perks are small-business conveniences and partner deals. The card is automatically enrolled in Mastercard Easy Savings, which gives automatic rebates at participating merchants, and business clients can load RBC Offers for savings on business spending.
Link the card for 3 cents per litre off fuel and 20% more Petro-Points at Petro-Canada, 3X Canadian Tire Money through Triangle Rewards, and a 6-month complimentary DashPass from DoorDash. Zero Liability fraud protection and Credit Card Lock in the RBC Mobile app are included. There is no travel credit or lounge access.
Insurance
The insurance covers business purchases only. Purchase security protects eligible business items against loss, theft or damage for 90 days, up to $50,000 per account per calendar year, and extended warranty doubles the manufacturer's warranty by up to 1 extra year, to a combined maximum of five years.
Items bought for personal use are excluded, and purchase security pays after your business insurance, so in practice it often covers the deductible. There is no travel, rental car or mobile device insurance; RBC sells travel insurance as an optional extra.
My take
I'd get this card if you run a small operation spending under $65,000 a year and want free, automatic cash back; if you need several employee cards or spend more than that, I'd skip it.
What I like is how little it asks: no fee, no categories, no minimum spend for the intro 2%, and the cash lands on the January statement without a phone call. For a side business or a new sole proprietorship that wants its spending off the personal card, that is a sensible start.
The $650 cap is the limit I'd watch. At 1% it is reached at $65,000 a year, and the single additional card makes it awkward for anything beyond an owner and one other person. The insurance is purchase cover only, so I'd look elsewhere if the business travels.
The good
- No annual fee, and the one additional card is free
- Flat 1% on everything, 2% for the first three months with no spend target
- Cash back credited automatically every January
The catch
- Cash back capped at $650 a year ($65,000 in spending)
- Only one additional card allowed
- Purchase cover only; no travel or rental car insurance