Some links on this page earn me a commission or referral bonus, at no cost to you. They never decide what I recommend. Learn more
A good credit card doesn't have to cost you anything. Some of the best value in Canada sits in cards with a $0 annual fee, especially if you're getting your first card or just don't want to think about whether a fee is "worth it."
I went through every no-fee card on this site and picked the 10 I'd actually use.
One thing to know before you apply: no fee doesn't mean no requirements. Some of these cards ask for a minimum income, which I mention below where it matters.
Short on time?Skip the list and see which one I'd get.
Jump to my pickBest overallCapital One Quicksilver World Elite Mastercard®
Welcome bonus2xcash back in year one
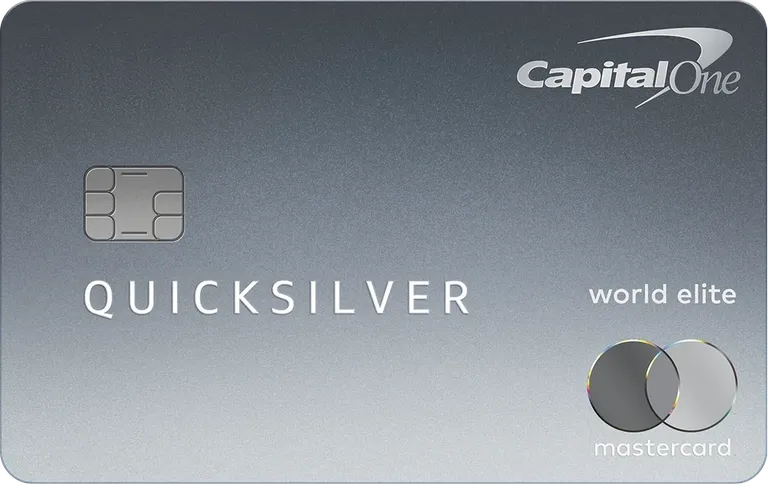
The Capital One Quicksilver World Elite Mastercard® is the best no-fee card in Canada right now. It pays 3% cash back on groceries and 3% on gas and EV charging, plus 1% on everything else.
It's also one of very few $0 cards with no foreign transaction fee. I got approved for it in October 2026.
The catch is the income bar: $80,000 personal or $150,000 household. If that's out of reach, the Capital One Quicksilver World Mastercard® has the same earn rates at $50,000 or $80,000.
Walmart, Costco and other superstores earn 1%, not 3%. There's no emergency medical or trip cancellation insurance either.
Best for AeroplanCIBC Aeroplan® Visa* Card
Welcome bonus, up to10,000Aeroplan pointsUp to $200 in travel (CIBC's estimate)
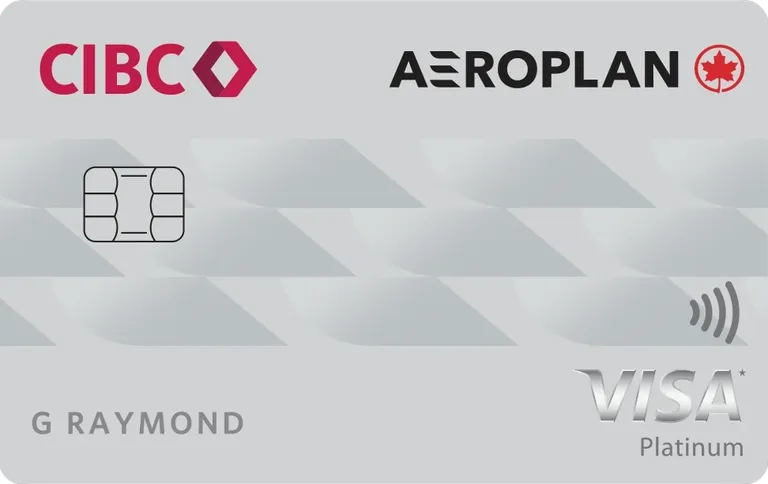
The CIBC Aeroplan® Visa* Card is the easiest way to earn Aeroplan points without a fee. It earns 1 point per $1 on gas, EV charging, groceries and Air Canada purchases, and 1 point per $1.50 on everything else.
You also get Aeroplan's cardholder pricing on flight rewards and primary rental car cover. From January 12, 2027, that pricing is a fixed 15% off the base-fare points on eligible Air Canada flight rewards.
Aeroplan points stretch further than cash back when you book flights well, and my Aeroplan beginner's guide explains how. Just know there's no free checked bag or lounge access, and the 2.5% foreign transaction fee makes it a poor card to use abroad.
Best for Scene+ pointsScotiabank American Express® Card
Welcome bonus, up toEnds Jul 1, 20275,000Scene+ pointsUp to $50 in travel (Scotiabank's figure)
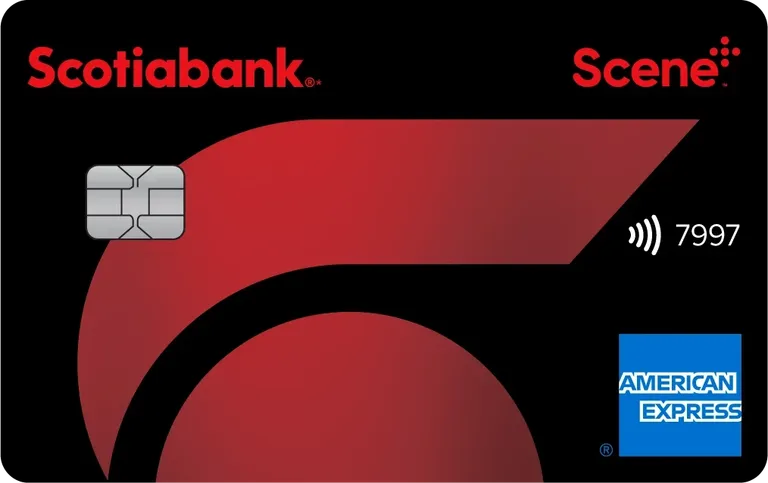
The Scotiabank American Express® Card earns more on everyday spending than most no-fee cards. You get 3x Scene+ points at Sobeys, IGA, Safeway, FreshCo and the other Sobeys-family stores.
Other grocery stores, restaurants, food delivery, gas, transit and streaming earn 2x. Scene+ points are worth a fixed 1 cent per point (cpp), so that's 2% to 3% back in the categories that matter.
You get mobile device insurance too, up to $500. As an Amex, it isn't accepted everywhere, so keep a Visa or Mastercard as backup. The higher rates stop after $50,000 a year, and there's a 2.5% foreign transaction fee.
Best for Membership RewardsAmerican Express® Green Card
Welcome bonus10,000Membership Rewards points$100 (Amex's figure)
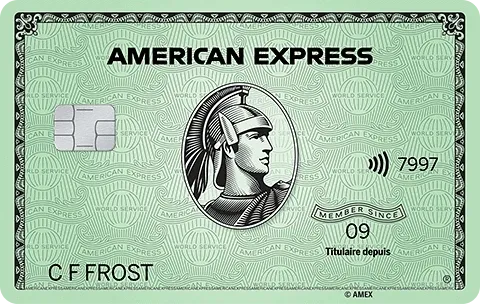
The American Express® Green Card earns full Membership Rewards points with no annual fee. It earns 1 point per $1 on everything and 2x on hotels and cars booked through Amex Travel.
What makes it special is the transfers: Membership Rewards points move 1:1 to Aeroplan and other programs, which can be worth well over 1 cent each. If you'd rather keep it simple, 1,000 points take $10 off your statement.
The everyday earn is modest, so this card works best next to a higher-earning card. Its insurance only covers purchases, and as an Amex, it isn't accepted everywhere.
Best for everyday categoriesRBC ION Visa‡
Welcome bonus, up toEnds Jan 12, 20277,000Avion pointsUp to $50 in gift cards (RBC's figure)
The RBC ION Visa‡ earns 1.5x Avion points at grocery stores, gas stations and EV charging, transit and rideshare, and on streaming and digital subscriptions. Everything else earns 1x.
You also get 6 months of DoorDash DashPass, and 3 cents a litre off at Petro-Canada with a linked card. If you bank with RBC, this card slots in easily.
The catch is what the points are worth on their own: most $10 gift cards start at 1,400 points. They go further if you also hold an Avion Visa, since the points can move to that account.
Want triple points instead? The RBC ION+ Visa pays 3x in the same categories, plus dining and food delivery, for $4 a month ($48 a year). It adds $1,000 of mobile device insurance, and it's the one in my wallet.
Best for Canadian Tire shoppersTriangle® World Elite Mastercard®
Welcome bonusNone right now
The Triangle® World Elite Mastercard® pays 4% back in CT Money at Canadian Tire, Sport Chek, Mark's and the rest of the Canadian Tire family. Grocery stores earn 3% on the first $12,000 a year, and everything else earns 1%.
At Gas+ and Petro-Canada, it earns 5 cents a litre on regular fuel and 7 cents on premium. You get a roadside assistance plan too, once you activate it: 5 service calls every 12 months, with tows up to 250 km.
The catch is where the rewards go: $1 in CT Money takes $1 off, but only at Canadian Tire family stores. You also need $80,000 in personal income or $150,000 household, and Walmart and Costco don't count as grocery stores.
Best for dining and billsBMO eclipse rise Visa* Card
Welcome bonusEnds Oct 31, 202725,000BMO Rewards points
The BMO eclipse rise Visa* Card pays 5 BMO Rewards points per $2 (2.5x) on groceries, dining and food delivery, and recurring bills like streaming and your phone. Everything else earns 1 point per $2.
You can also earn up to 5,000 bonus points a year, and it comes with $1,000 mobile device insurance. Half of the bonus is for paying in full on time for 12 straight months, and half for redeeming at least 12,000 points a year.
BMO points are worth about 0.67 cpp, so the real return is about 1.67% in the bonus categories. Each category is also capped at $5,000 a year, and there's a 2.5% foreign transaction fee.
Best cash back AmexSimplyCash® Card from American Express
Welcome bonus, up to5%cash back · first 3 months
The SimplyCash® Card from American Express is cash back without any thinking. It pays 2% on gas and 2% on groceries, and 1.25% on everything else, with no categories to pick.
The 2% stops after $15,000 a year of gas and groceries combined, and superstores and wholesale clubs don't count. The cash back pays out once a year, in September.
Like the other Amex cards, it isn't accepted everywhere.
Best for choosing your categoriesTangerine® Money-Back World Mastercard®*
Welcome bonusEnds Nov 30$120cash back
The Tangerine® Money-Back World Mastercard®* lets you choose your own 2% categories: two of them, or three if you have your cash back paid into a Tangerine savings account. Everything else earns 0.5%.
There are 13 categories on the list, from groceries, restaurants and gas to recurring bills, and the 2% isn't capped. It also comes with mobile device insurance and rental car cover.
It's the most flexible card on this list, but the 0.5% base rate is low. You also need $50,000 in personal income or $80,000 household to qualify, or $250,000 in Tangerine savings and investments.
Best for Rogers customersRogers Red World Elite® Mastercard®
Welcome bonusNone right now
If you have a Rogers, Fido, Shaw or Comwave service, the Rogers Red World Elite® Mastercard® pays 2% on everything (1.5% without one), plus 3% on U.S. dollar purchases. Since November 18, 2026, bills and online purchases from those brands earn 5%.
It also gives you $1,000,000 in emergency medical insurance, for the first 15 days of a trip if you're 64 or under. That's rare on a $0 card, but trip cancellation cover was removed on November 18, 2026.
With a Rogers postpaid mobile plan, you get 5 Roam Like Home days a year, which become a $75 annual roaming credit on January 12, 2027. The catches are a 2.5% foreign transaction fee that eats most of that 3%, and an income bar of $80,000 personal or $150,000 household.
Which One Should You Get?
For most people, I'd start with the Capital One Quicksilver World Elite Mastercard®. If its income bar is out of reach, the Scotiabank American Express® Card asks for only $12,000 and still pays 2% to 3% back on groceries.
If you want travel points instead of cash, the CIBC Aeroplan® Visa* Card is the easiest no-fee way into Aeroplan. Paying a fee can still make sense if you spend a lot.
FAQ
Is a No-Fee Card Good Enough?
For everyday spending, yes. The best cards here pay 2% to 3% back on groceries and gas, and my top pick has no foreign transaction fee.
What you give up is mostly travel insurance and perks. None of the 10 comes with free lounge visits, and only one includes emergency medical insurance.
Can I Earn Points Without an Annual Fee?
Yes. The CIBC Aeroplan® Visa* Card earns Aeroplan points directly, and the American Express® Green Card earns Membership Rewards points that transfer 1:1 to Aeroplan.
The earn rates are modest, at 1 point per dollar or less on most purchases, so the points build slowly. Three other cards on this list earn Scene+, Avion or BMO Rewards points.
Are the Welcome Offers Up to Date?
Yes. They come straight from each card's page on this site, so this page changes as soon as a card's page does.
Most cards are checked against the issuer's own site every week, and I review all of them once a month.
Do You Earn Money When I Apply?
Some Apply buttons are referral links, which may earn me a bonus if you're approved, at no cost to you. They never decide which card I pick.
Why Isn't My Card Here?
This list has the 10 no-fee cards I'd pick. The best credit cards by category page has my favourite in each category, and the credit card catalogue lets you search and compare every card I track.
Checked Nov 21, 2026 · Sources: Capital One Quicksilver World Elite Mastercard · CIBC Aeroplan Visa Card · Scotiabank American Express Card · American Express Green Card · RBC ION Visa · RBC ION+ Visa · Triangle World Elite Mastercard · BMO eclipse rise Visa Card · SimplyCash Card from American Express · Tangerine Money-Back World Mastercard · Rogers Red World Elite Mastercard